Why Your Insurance Premium Went Up Even Though You Never Filed a Claim
A clean driving record. No burst pipes, no break-ins, no calls to your agent all year. And yet the renewal notice arrives with a bigger number anyway. The reason has almost nothing to do with you personally — and almost everything to do with everyone else.
Why Your Insurance Premium Went Up Even Though You Never Filed a Claim
A clean driving record. No burst pipes, no break-ins, no calls to your agent all year. And yet the renewal notice arrives with a bigger number anyway. The reason has almost nothing to do with you personally — and almost everything to do with everyone else.
Anurag Soni
August 24, 2026
Sponsored by

AI agents built to get work done

Skydive agents take on work for you, using the same tools your team already uses.
Talk to your agent on the web, Slack, email, iMessage, or right from your terminal. Wherever you pick up the conversation, your agent keeps the context.
Put agents to work across customer support, sales, marketing, engineering, ops, and more.
Give your agent a job. They’ll take it from there.
Your premium went up anyway.
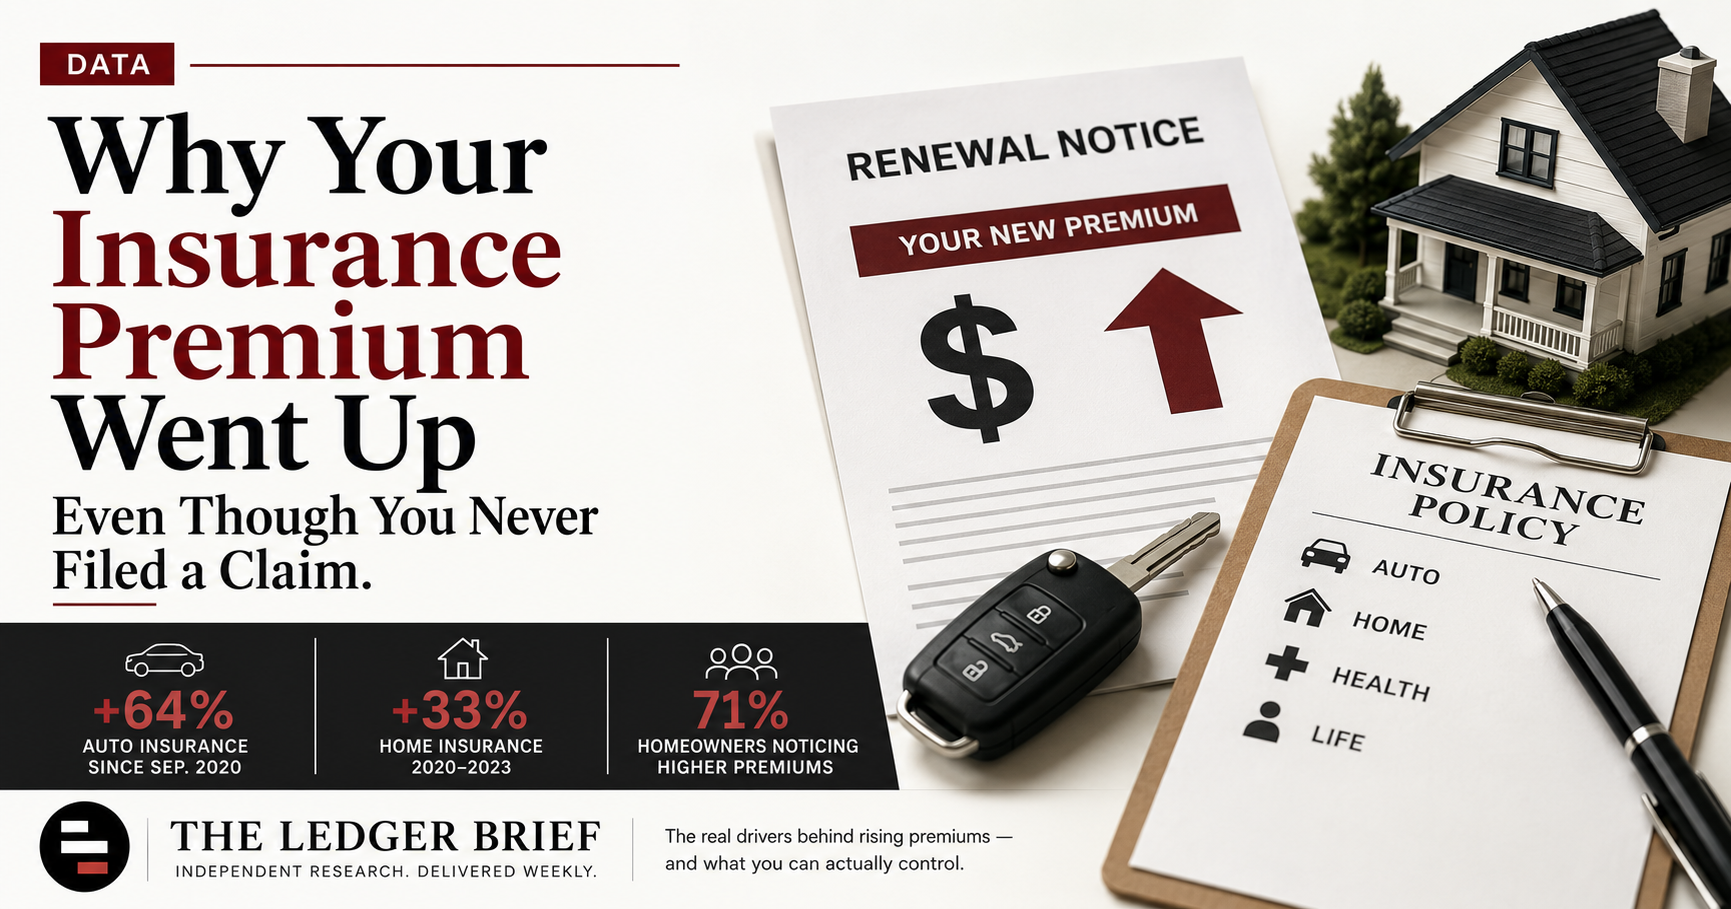
+64% AUTO INSURANCE SINCE SEP. 2020 | +33% HOME INSURANCE 2020–2023 | 71% HOMEOWNERS NOTICING HIGHER PREMIUMS |
There's a specific kind of frustration that comes with a clean record and a rising bill. You didn't crash the car. You didn't file a claim. Nothing happened, as far as you're concerned — and the renewal letter still shows a bigger number than last year's.
The math behind that frustration is national, not personal. Auto insurance premiums have climbed more than 64% since September 2020, according to Bureau of Labor Statistics data — nearly triple the 25% general inflation rate over that same stretch. Home insurance rose 33% between 2020 and 2023 alone, and climbed another 3.3% in 2024, well above its historical average yearly increase of under 2%. Pew Research found 71% of homeowners report noticing the increases directly, which means this isn't a fringe complaint — it's most people's actual experience.
Your individual record barely moves the number anymore
Here's the part that reframes the whole situation: your personal claims history remains a real factor in what you pay, but it's increasingly a smaller factor relative to forces that have nothing to do with you. Insurers set rates based on aggregate loss ratios across their entire book of business in a given region — meaning if enough of your neighbors filed claims after a hailstorm, a wildfire, or a flood, your premium can rise even though your own house never took a scratch.
That's not a bug in how insurance works. It's the entire premise of insurance — pooling risk across a group. The uncomfortable update for 2026 is how much more volatile that pooled risk has become, and how directly it now shows up in individual bills.
Insurance was always about the group, not the individual. What changed is how visibly the group's bad year now shows up in your personal mailbox.
By the numbers
Cumulative rise in U.S. auto insurance premiums, September 2020 to September 2025.
General inflation over that same period, for comparison.
Home insurance premium increase from 2020–2023.
Share of homeowners who report noticing premium increases directly.
Average rise in home insurance deductibles in 2025 alone.
Average increase in ACA marketplace health insurance premiums for 2026.
| 64% |
| 33% |
| 25% |
The three forces actually driving this
Three separate pressures are compounding at the same time, which is part of why the increases have felt so relentless rather than a one-year spike that corrects itself.
The part that's actually within your control
None of this means your own choices are irrelevant — they're just a smaller lever than the regional trend. Comparing quotes across insurers remains the single highest-impact action available to most people; rate differences of several hundred dollars a year for identical coverage between insurers in the same market are common, since each company weighs the same regional risk data slightly differently. Raising your deductible, bundling policies, and maintaining a strong credit score (which most states still allow insurers to factor into pricing) all help too — but none of them will fully offset a market-wide trend that's driven by claims you had nothing to do with.
What this means for your portfolio
For investors in property and casualty insurers, the “rate adequacy” story matters directly to underwriting margins — insurers that spent the last several years pushing through these increases are, by most industry accounts, back to profitability on underwriting after a rough multi-year stretch, which is a meaningfully different setup than betting on further rate hikes indefinitely.
For homeowners specifically, the shift toward higher deductibles and more granular, property-level underwriting — satellite imagery, drone inspections, AI-driven risk assessment — is worth understanding as a structural change, not a temporary inconvenience. Insurers are increasingly pricing individual properties rather than broad regional averages, which means two houses on the same street can see meaningfully different premium trajectories going forward based on specific, inspectable risk factors like roof age and defensible space.
What we're watching next
Whether the recent stabilization in insurance pricing holds, or whether the next major weather event resets the cycle. Insurify's own 2026 outlook already projects rate increases in 32 states by year's end, which suggests “stabilization” may be more of a pause than a genuine turning point.
1. Yahoo Finance — “2026 insurance outlook: Costs will rise as technology evolves” · BLS data
2. WalletHub — “Home Insurance Premium Statistics for 2026”
3. ECIKS — “Insurance costs rising across auto, health, and home coverage in 2026” · Pew Research data
4. Matic — “2026 Home Insurance Predictions”
Illustrative figures and third-party research cited above; not investment or insurance advice.